

Nearly every seller looks up an online estimate of their home before they call anyone. It is free, instant, and oddly authoritative, and it is usually the number in the back of someone's mind when we first talk. It is worth understanding how that figure is produced, because once you know what goes into it you can see exactly where it is useful and where it is likely to be a long way out.
How an automated estimate is built
An automated valuation is a statistical model. It assembles what is on public record for your property, the tax assessment, recorded sales, square footage, lot size, year built, bedroom and bathroom counts, adds whatever listing data it can see nearby, and infers a value from recent sales of properties it treats as similar.
That is a reasonable way to approach a question at enormous scale, and these models are genuinely good at the problem they are built for: estimating typical houses in large, uniform neighborhoods where plenty of near-identical homes have sold recently. The further your property sits from that description, the more the estimate is extrapolating.
The thing to hold onto is that nobody looked at your house. No part of the number comes from anyone standing in your kitchen.
What the model cannot see
Condition is invisible to it. A house with a new roof, replaced windows, and a renovated kitchen and the identical house that has had nothing done since it was built look the same in public records. So does the difference between a careful renovation and an amateur one.
Layout and light are invisible too, as is anything about the setting. Backing onto woods rather than a highway, a view, morning versus afternoon sun on the deck, a steep driveway, a dated floor plan, an awkward addition: all of these move what a buyer will pay and none of them appear in the data.
Permit records and tax data also lag, and they are not uniform between counties. If your square footage is recorded incorrectly, or an addition never made it onto the tax card, the model is working from the wrong house and will be confidently wrong.
Waterfront and rural property breaks these models hardest
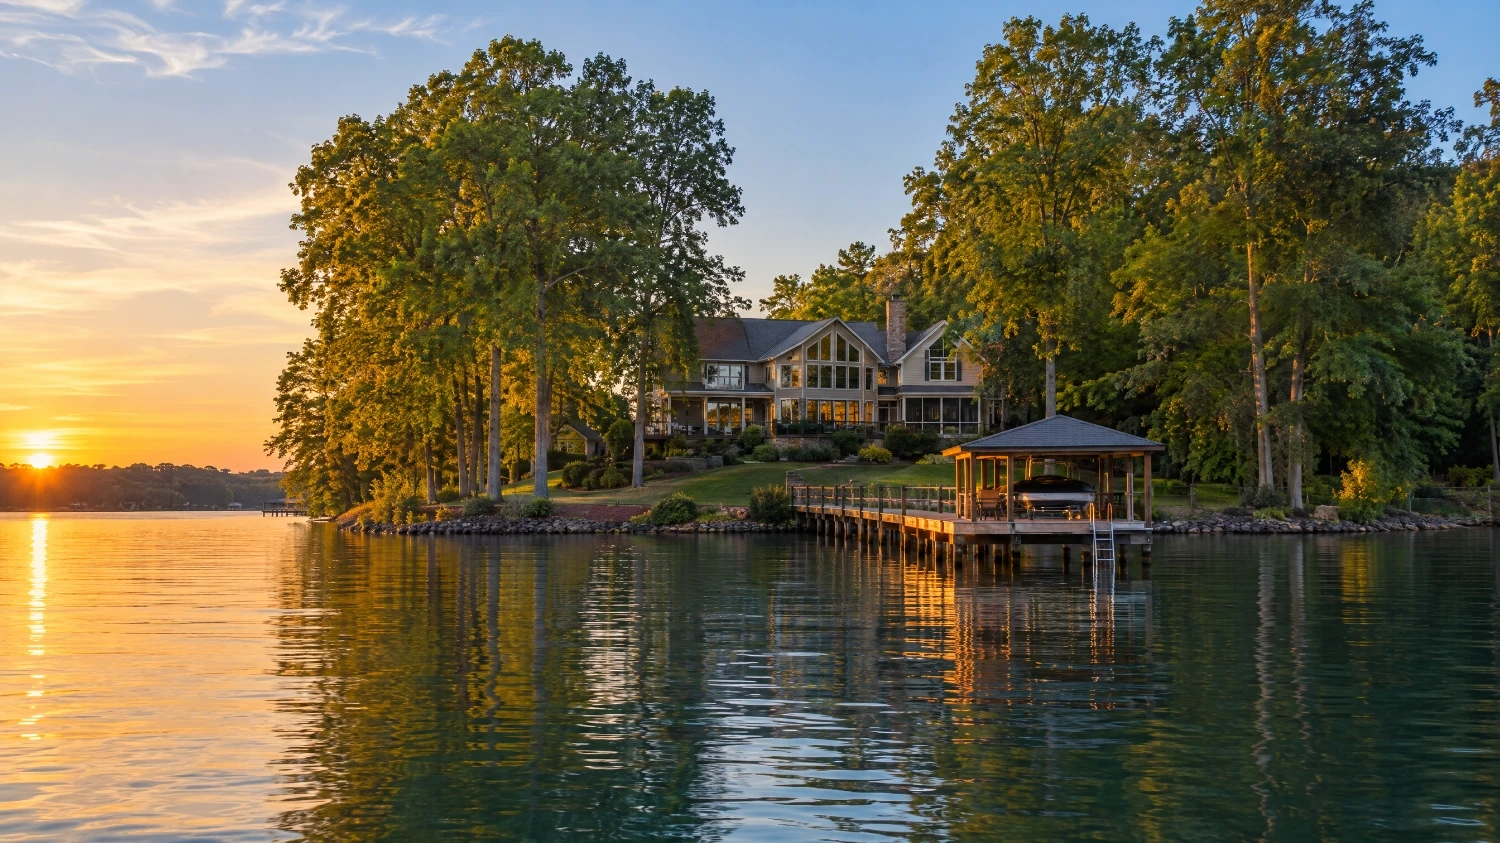
This is the part that matters locally. Automated estimates rely on volume, and distinctive property does not provide it. On the lake, two homes a few hundred feet apart can be worth very different amounts because of water depth, the direction the lot faces, whether the shoreline is usable, what sort of dock is permitted and already in place, how much frontage there is, and whether the lot is on a quiet cove or open water.
A model sees a waterfront house and other waterfront houses that have sold. It does not see that one of them has a deep-water dock and a southern exposure and the other has a seasonal mudflat and no permit. With few truly comparable sales to lean on, small differences in the inputs swing the output a long way.
Acreage causes the same trouble for different reasons. Land value does not scale in a straight line, and whether a tract is wooded, cleared, tillable, fenced, divisible, or has a second homesite changes what it is worth in ways no public record captures. The same goes for an older house on a large lot where much of the value is in the land.
Where the number is genuinely useful
It is a fine place to start. If you are a couple of years out, checking an estimate occasionally gives you a rough sense of direction without anyone having to do real work. It is also useful as a sanity check: if your expectation and the estimate are wildly apart, one of you is working from something the other cannot see, and that is worth understanding.
What it should not be is the basis for a list price. Pricing from an automated estimate pulls in both directions. Priced too high, a house sits, and the longer it sits the more buyers assume something is wrong with it. Priced too low, you may sell quickly and leave money behind. Our post on how long a sale actually takes covers what the first weeks on the market do to the outcome.
What a real valuation involves
Someone walks the property. They look at condition, updates, layout, the setting, and the things that make your house different from the one down the street. Then they choose genuinely comparable sales rather than statistically similar ones, and adjust for the differences that remain, which is where the local knowledge earns its keep. On the lake that means knowing which coves and which streets command what, and why.
An appraisal is a related but separate exercise, usually ordered by a lender once a property is under contract, and it answers the lender's question rather than yours. If you are curious whether to get one before listing, we wrote about getting an appraisal before you sell, including when it is worth it and when it is not.
A valuation from us is free and carries no obligation, and we will tell you plainly if what you want to achieve is not realistic. If you are weighing up what a sale would actually net you, read it alongside what it costs to sell a home in North Carolina, and our home selling process page walks through what happens after that.
Gonzalez Realty is an Equal Housing Opportunity firm. We do not discriminate on the basis of race, color, religion, sex, handicap, familial status, or national origin.
This post is for general educational purposes only and is not legal, tax, or financial advice. Real estate laws, loan programs, and market conditions change over time, and older posts may not reflect current details. Confirm specifics with your agent, a real estate attorney, a lender, or a tax professional before making a decision.
Portions of this content were drafted with AI assistance and reviewed by our team before publishing. Nothing on this page creates a client relationship with Gonzalez Realty.