

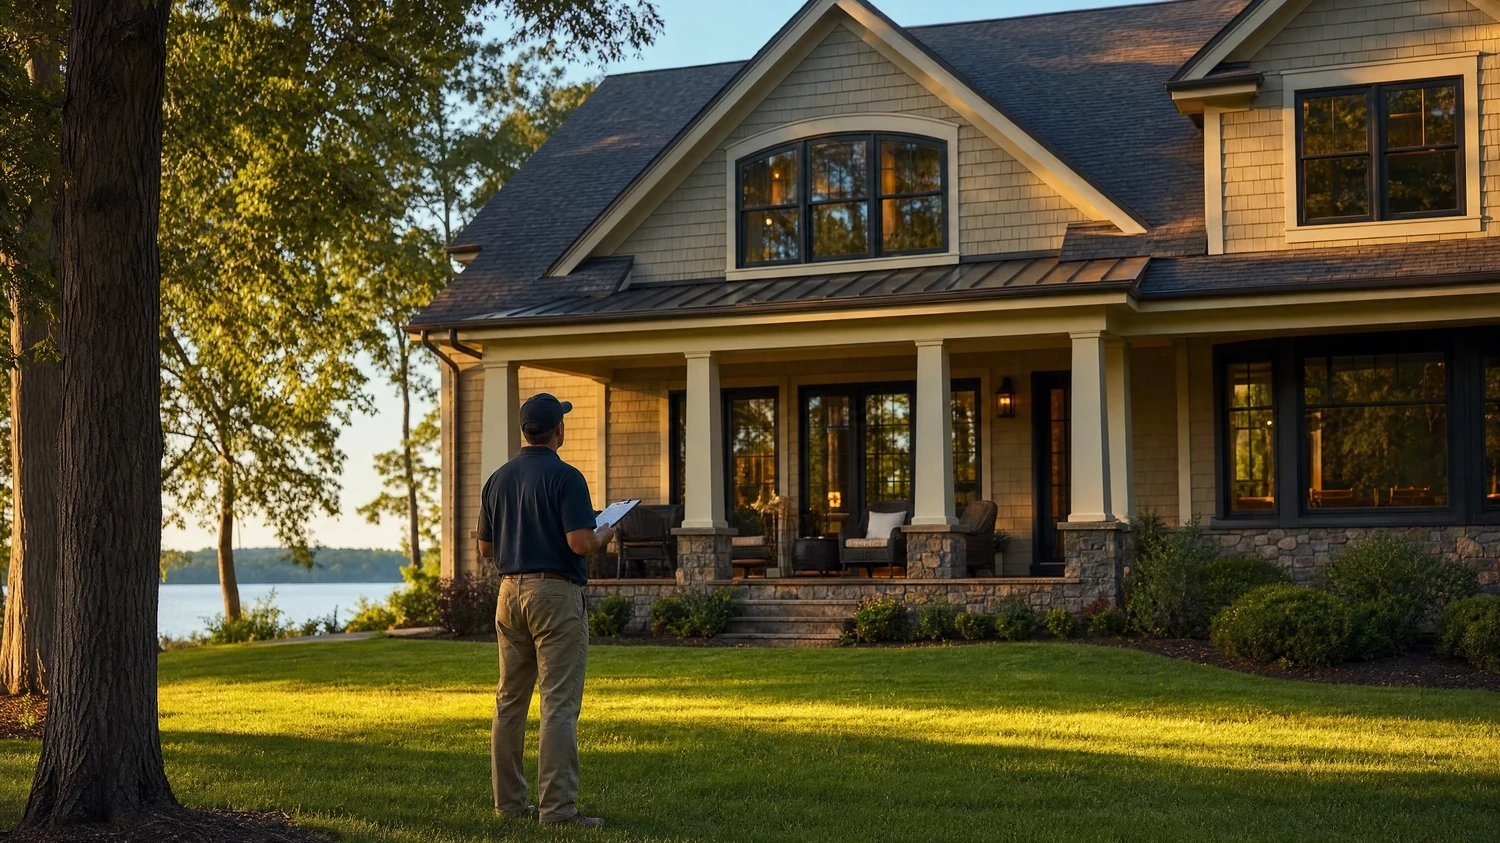
A pre-listing appraisal sounds like the responsible way to price a home: pay a licensed professional, get an objective number, list from there. Sometimes it is exactly that. More often it answers a slightly different question than the one a seller is asking, and it does not replace the appraisal your buyer's lender will order anyway.
An appraisal, a market analysis and an online estimate are three different things
An appraisal is a formal opinion of value from an appraiser licensed or certified by the North Carolina Appraisal Board. It is built from recently closed sales, adjusted for differences between those homes and yours, and it is written to a professional standard.
A comparative market analysis from an agent uses the same closed sales but also weighs what is active, pending and sitting unsold, which is the competition your buyer will actually tour. It is a pricing strategy rather than a valuation.
An automated online estimate is an algorithm working from public records and listing data. It cannot see your renovated kitchen, your water frontage or the road noise, and it is the least reliable of the three for any home that is not a typical one.
Your buyer's lender will order its own appraisal regardless
If your buyer is financing, the lender orders an appraisal through its own channels, and appraiser-independence rules mean it will not simply accept one you paid for. So a pre-listing appraisal is not a shortcut through the buyer's appraisal. At best it is a preview of it.
That preview has value mainly when you have reason to think the lender's number might come in low. How that appraisal works from the buyer's side, and what happens when it disappoints, is covered in our buyer's guide to home appraisals.
When a pre-listing appraisal is worth paying for
It earns its fee when comparable sales are thin or hard to read. Lakefront homes are the local example: on Lake Norman, two houses on the same road can differ in frontage, water depth, dock, cove versus open-water views and how the lot slopes to the shoreline, and every one of those moves value.
It also helps when a number needs to be defensible to people other than a buyer: an estate being settled among heirs, co-owners or a divorcing couple who disagree on price, or a seller going it alone without an agent's market analysis. In those cases the independence of the appraisal is the point.
For a typical home in a neighborhood with regular sales, an agent's market analysis usually tells you more for pricing purposes, and is usually free.
How far above appraisal should you list?
There is no standard markup, and a rule of thumb would mislead you. An appraisal looks backward at what has already closed. A list price looks forward at what a buyer will pay against the homes they can see this week. Sometimes those agree and sometimes they do not.
The practical ceiling is what an appraiser will support when the buyer's loan comes due. Price well above it and you may still get an offer, but a low appraisal then forces a renegotiation, a buyer bringing extra cash, or a contract that falls apart. Pricing near a supportable number tends to produce fewer surprises than pricing high and hoping.
A more useful question to start with
Rather than asking what a single appraisal says, ask what the recent sales and the current competition say together, and how much room there is between them. That range is what pricing decisions are really made inside.
If you want to see how that plays out for your home, our home valuation page is the place to start, and the wider home selling process guide shows where pricing fits in the sequence.
This is general information, not legal advice; confirm specifics with your agent or a real estate attorney.
Gonzalez Realty is an Equal Housing Opportunity firm. We do not discriminate on the basis of race, color, religion, sex, handicap, familial status, or national origin.
This post is for general educational purposes only and is not legal, tax, or financial advice. Real estate laws, loan programs, and market conditions change over time, and older posts may not reflect current details. Confirm specifics with your agent, a real estate attorney, a lender, or a tax professional before making a decision.
Portions of this content were drafted with AI assistance and reviewed by our team before publishing. Nothing on this page creates a client relationship with Gonzalez Realty.